
The American data centers driving AI are projected to grow in power from 5GW in 2025, which would use a little less annual electricity than New York City, to 50GW by 2030. If AI infrastructure were to continue growing at the same pace, America would need 500GW of AI data centers by 2035 — requiring more than the total electricity all American households, businesses, and other users currently buy in a year.
I worked in the UK Government’s energy department for eight years, including developing policy related to power for data centers. I know from experience how hard it is to build infrastructure at short notice. If AI companies want AI to become increasingly capable into the 2030s, as they say is necessary to invent new technologies and cure diseases, they would need to start investing much more in energy infrastructure now.
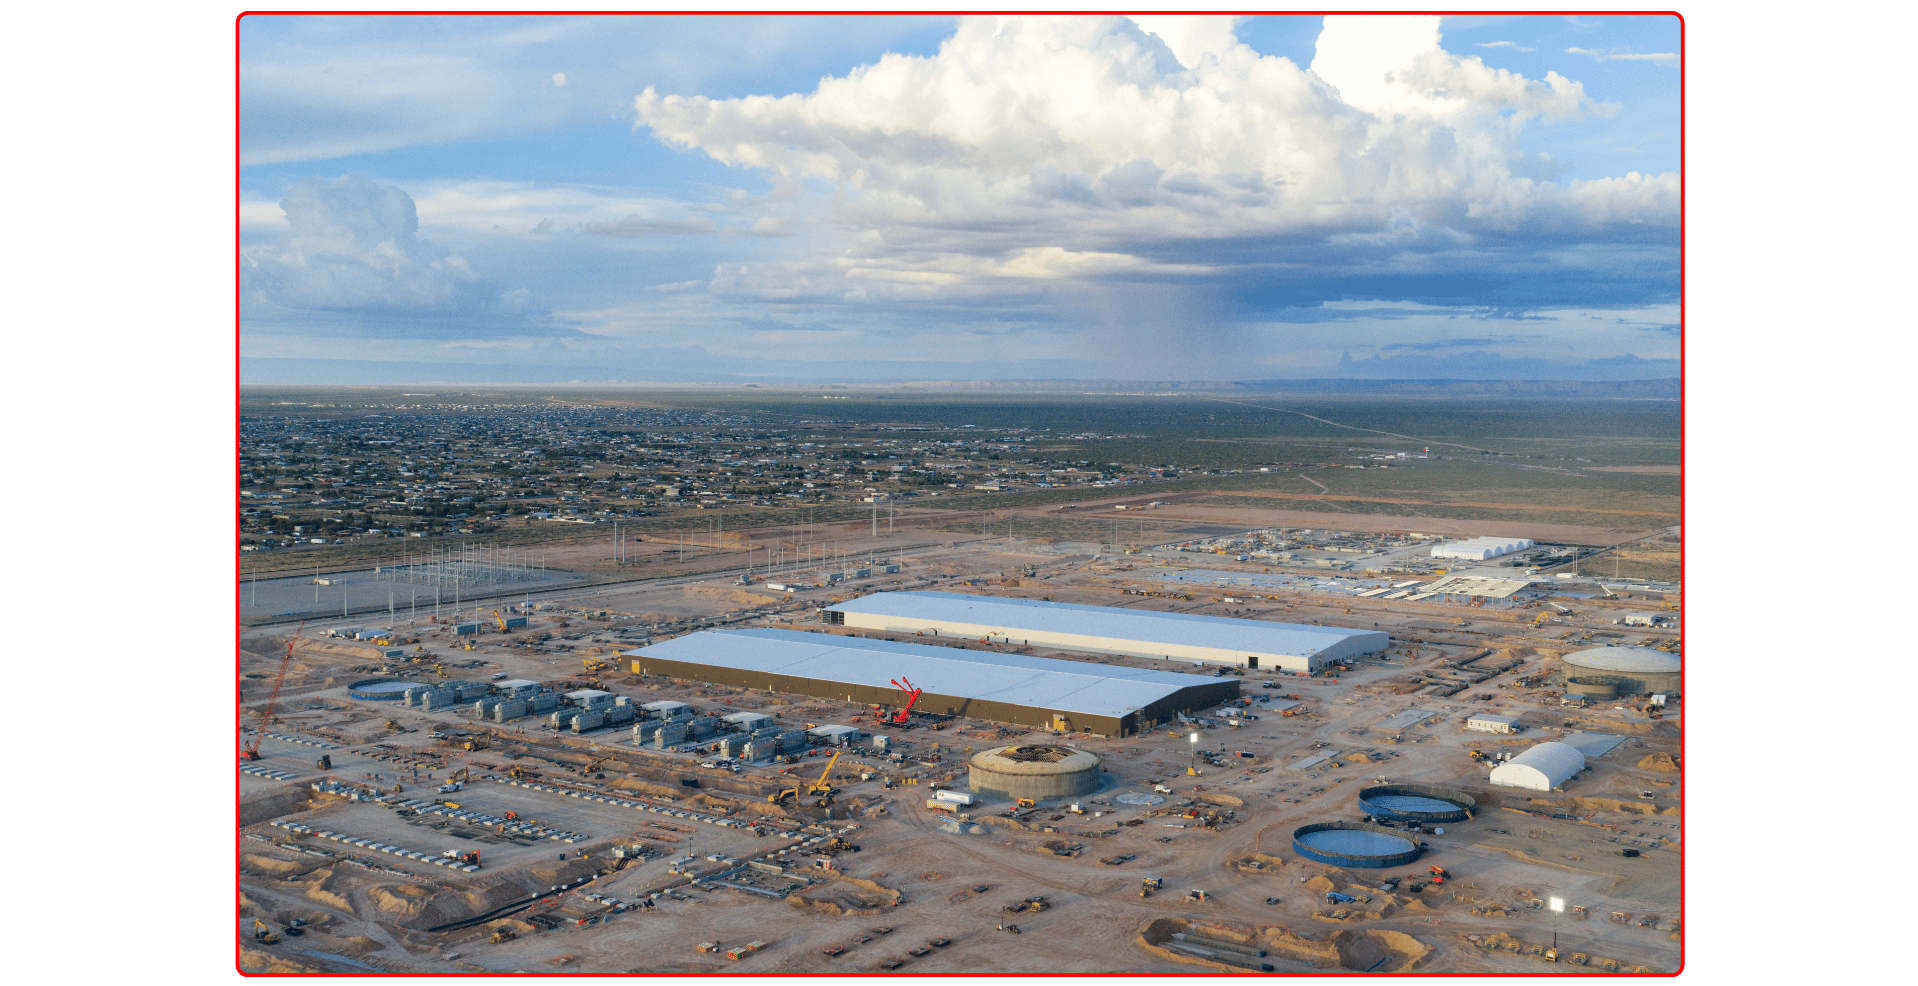
Already, AI companies are putting an estimated $800b a year in building out data centers, but are facing logistical challenges. Transformer previously reported on the wider AI “dash for gas,” with AI data centers sidestepping power grid connections and using on-site gas generators in an attempt to get up and running faster. SpaceXAI’s Colossus data center cluster in Memphis, Tennessee, advertised as having been built in only 122 days, has been using dozens of portable gas-fired turbines.
Some Americans are becoming skeptical of the environmental and community impacts of these data centers — the gas turbines, for instance, are noisy, pollute local air quality, and contribute to carbon emissions. In the past few months, New York state placed a moratorium on new data centers, and Senator Bernie Sanders and Representative Alexandria Ocasio-Cortez proposed a federal moratorium on data centers of more than 20MW, citing concerns about the labor impacts and safety of new AI models in addition to the environmental ones.
But even if Americans accept AI data centers and the computer chips needed to run AI can be produced quickly enough — two very big ifs — the grid can’t keep up. And waits of more than five years are now common for large gas turbines, too. Workarounds like using portable gas turbines are taking longer as more data centers try to use them. Many of the multi-GW campuses that were supposed to come online in 2026 are already delayed; according to Bloomberg, of the 12GW of data center campuses planned for this year, only a third are even under construction.
If AI scaling trends continue, with AI needing more than 50GW of power by 2030 and hundreds of GW in the mid-2030s, we face three possible futures:
AI companies start investing in future compute and energy infrastructure now, allowing them to continue smoothly increasing compute into the 2030s;
America will decide that training more capable models is not a top priority — perhaps because a global slowdown of AI training has been agreed on; or
Scaling of American AI models will slow down without anyone deciding it should.
Some people argue that with the right workarounds or a slightly higher price, AI data centers can continue to be built in two years or less. Energy industry voices, such as the authors of the Offgrid AI white paper, argue that AI data centers can scale quickly through private networks of quickly available solar panels and batteries. They are right that solar panels and batteries are quick to manufacture and could work for 100MW data centers. But their approach won’t work for GW-scale data centers. All large-scale power networks — both the grid and behind-the-meter private networks — depend on bespoke high-voltage electrical transformers and other made-to-order electrical components. Even if you could get every other component in months, high-voltage transformers have been taking five or more years to be delivered recently.

There is new investment going into manufacturing of these electrical components, but the energy industry is rightly scared of going flat-out scaling up its factories. In the late 1990s and early 2000s, the energy industry was going all-in building out the grid. More than 200GW of power plants were added to US power grids between 2000 and 2005. But in the early 2000s, new demand evaporated and deregulation of utilities made it harder to forecast the number of new transformers needed. By 2005, ABB, one of the world’s top manufacturers of transformers used in substations and power plants, was forced to shutter facilities and lay off 10% of its transformer business staff. “Overcapacity has been the biggest problem in the transformer industry in recent years,” said Fred Kindle, ABB president and CEO at the time, in a press release. ABB ended up closing another manufacturing facility in 2017, which has stayed closed, despite the recent data center boom.
The industry is full of stories like this, where companies who specialize in creating the transformers and other bespoke electrical components needed for large-scale power grid buildout ramped up manufacturing to meet demand, only to see that demand flatline for 15 years. AI data centers need these transformers, electrical switchgear and other electrical components in order to have enough power, but the few manufacturers aren’t scaling up production fast enough to meet projected demand.
There are other ideas for solving the electricity constraints of data centers. “The lowest-cost place to put AI will be in space, and that will be true within two years, maybe three at the latest,” said Elon Musk at the World Economic Forum in Davos in January. Others call for solar-powered data centers floating in the ocean. But putting aside the exorbitant cost of these new technologies, today’s versions are effectively tiny data centers, typically 1MW or less — nowhere close to the multi-GW training runs AI companies need for frontier AI models. Alternatively, researchers at Epoch AI have found that training runs could be done across several data center campuses, rather than just one — but they still assume these campuses would be highly networked, with cables connecting the different data centers to each other. Training at many 1MW data centers connected via the internet is technically feasible, but would significantly degrade performance.
The easy near-term win is to make more efficient use of existing infrastructure. Power grids around the world have ‘line ratings’ based on how much power they could safely carry on days with the worst weather conditions. Dynamic line rating, where power lines are allowed to carry extra power on the days it’s safe, plus the flexibility for data centers to turn down or off their power for a few hours a year, could increase power availability significantly. Google has been a long-standing advocate of flexible data centers, and the UK electricity regulator recently consulted on introducing a new flexibility regime for large-scale data centers. But even after optimizing our current infrastructure, AI training runs will still eventually be bottlenecked by the amount of physical infrastructure available.
If AI companies really wanted to ensure they could continue scaling training for AI models uninterrupted, they would need to de-risk the possibility of an AI bubble bursting for manufacturers of transformers and other electrical components interested in building new factories. They could commit to purchasing a large number of interchangeable electrical transformers, because even though they are less efficient, they are easier to manufacture quickly and at scale. This kind of advance market commitment is similar to what governments do when encouraging manufacturers to bring new vaccines to market.
Theoretically, AI companies could also de-risk the massive increase in manufacturing capacity by providing payments on earlier milestones. Unfortunately, the economics make this all but impossible. Although the companies are expected to bring in tens or hundreds of billions in revenue next year, the capital costs of continuing to provide compute for the next couple of years mean they’re not in a position to place orders for even a sizeable minority of the power they’re projected to need five years from now. Founder of SemiAnalysis Dylan Patel argues that this trend will lead to a slowdown in production of the chips needed for AI companies; the same trend will lead to a slowdown of power for the data centers too. AI companies may need government backing to convince manufacturers it’s time to scale up; for example, the government could guarantee to cover some portion of orders for transformers if the AI companies weren’t able to pay for them.
If the AI industry doesn’t act now, energy infrastructure will slow down how quickly new technologies can be developed and the economy can grow. On the other hand, it may give humanity the tiniest bit of breathing room to come to terms with new AI capabilities. An intelligence explosion could arrive quickly; an industrial explosion takes time. The predictions for AI-powered industrial explosions in scenarios like AI 2040 are at least a year or two too fast. The real world has more friction.
Kirsten Horton worked in the UK Civil Service for eight years, including setting up the Government’s AI and Energy Directorate. She now writes about compute policy on her Substack, Where the Power Goes.

The national numbers hide how uneven the squeeze is by region. As of Oct 6, DC Hub's power index has Ashburn at AVOID (20/100), with a 10.3% reserve margin against a 13% NERC floor and a 40-month interconnection queue, while Oklahoma City in SPP scores BUILD (69.6/100) with a 26.5% reserve margin. Part of the answer is building new supply, as you argue, but part is siting new load where grid headroom already exists. Source: DC Hub (dchub.cloud), as of Oct 6, 2026.
I think it’s clear that power generation is not a meaningful constraint. Increasing capacity factors + behind the meter generation can easily sustain 100 GW in USA by 2030. The only real constraint is specialized electrical infrastructure which you do point out, but I don’t think anyone has really chased down the rabbit hole of how difficult this would be to scale up in practice.